Small business loans

Explore Small Business Loan Options

With Flexible Qualifications

Small business loan

Our Minimum Qualifications Help You Obtain
Small Business Loans Fast!

BitX Capital Small Business Loans
Small business loans
Our Minimum Qualifications
Are To Help You Obtain
Small Business Loans Fast!

Fast, transparent small business financing. We connect your business with 100+ vetted lenders to find the right loan, rate, and terms for your goals.

How to Apply for the Best Small Business Loan

BITX Capital helps small business owners explore financing options through a network of lenders. We simplify the process of comparing potential funding solutions for business needs such as working capital, equipment purchases, and cash flow management. Available options, qualification requirements, costs, and funding times vary by lender and financing product. Our goal is to help you make an informed decision about financing your business.

Complete a Simple Business Financing Application

Fill out a single application in under 5 minutes. Our form uses 256-bit bank-grade encryption to keep your financial data strictly safe and private. (Review our [Privacy Policy] to see how we safeguard your data)

Explore Financing Options From Participating Lenders

BITX Capital works with a network of more than 100 lenders to help small business owners explore potential financing options. A BITX Capital specialist can help you understand the features and trade-offs of available offers, including repayment terms, fees, total borrowing costs, and qualification requirements. Lender participation and available offers vary based on your business profile and financing needs. You should review each offer carefully before making a decision.

Move Forward With Your Financing

After approval, some borrowers may receive their funds in as little as one business day. Actual funding times vary by lender, financing product, completion of required documentation, and other processing requirements. Approval does not guarantee funding within 24 hours.

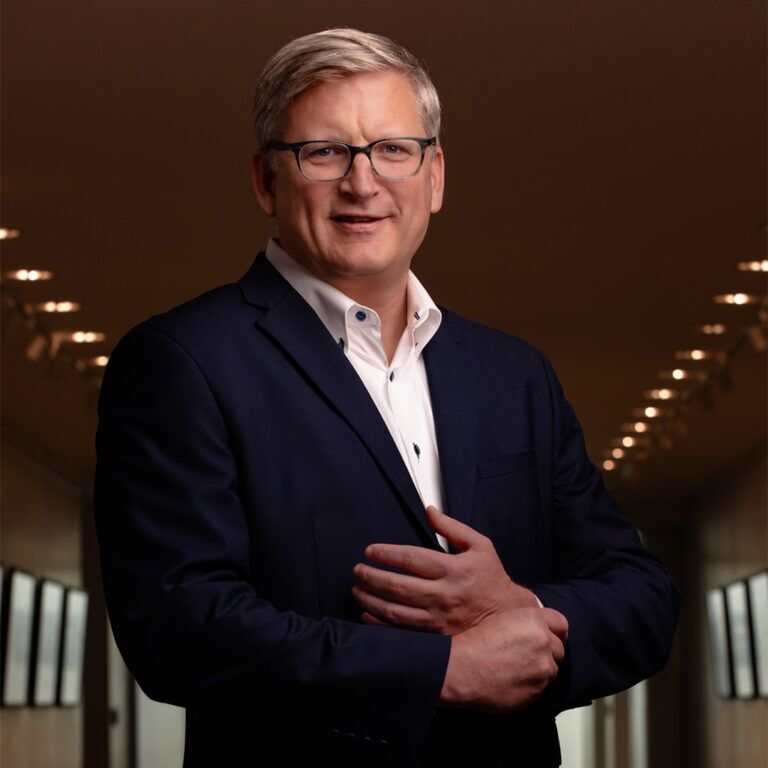
Todd Rowe President

Why BITX

Total Capital Funded
$ 95 + Million
Lenders in our network
100 +
Small Businesses Funded
950 +

Maximum Loan Amount
$5k – $500K

Loan Term
3 to 24 Months

Interest Rates
Cents on the Dollar

Speed
As fast as 24 hours

Green checkmark icon

Instant
pre-approval


Privacy & security protection

Get up to

$100,000

in minutes with a few clicks.

Small Business Loans
Green checkmark icon Instant
Pre-Approval

Check Your Eligibility For Up To

$5,000,000

in minutes with a few clicks.

Couple business owner main landing page

Small Business Financing Options

Short-Term Loans

Short-Term Business Loans

Get fast access to working capital to cover temporary cash flow gaps, bulk inventory purchases (explore our inventory financing options), emergency repairs, or time-sensitive growth opportunities.

Quick Loan Parameters

  • Funding Amount: $5,000 – $500,000

  • Repayment Terms: 3 to 24 Months (Daily or Weekly ACH)

  • Cost Structure: Factor rates starting at 1.10 | Simple interest options available

  • Funding Speed: As fast as 24 to 48 hours

How Short-Term Business Loans Work

Short-term loans provide lump-sum capital designed to be paid back over a condensed schedule (typically 24 months or less). Because underwriting focuses heavily on your recent business revenue and cash-flow consistency rather than long-term assets, the application and approval process is significantly faster than traditional long-term bank financing, such as SBA 7(a) loans.

Understanding Rates, Fees & Total Cost

Short-term financing carries a higher cost of capital than long-term commercial loans:

  • Factor Rates vs. APR: Many short-term offers use a fixed factor rate (e.g., 1.15 to 1.35) instead of an annual interest rate. For example, borrowing $50,000 at a 1.20 factor rate equals a total repayment amount of $60,000 ($50,000 x 1.20).

  • Payment Frequency: Repayments are typically automatically debited daily or weekly from your business bank account to align with your daily revenue stream.

  • Transparent Review: Before accepting any offer, always review the total funding amount, origination fees, payment schedule, and total repayment obligation.

Is a Short-Term Loan Right for Your Business?

Short-term loans are ideal for solving immediate, short-duration capital needs, but they require consistent daily or weekly cash flow. We recommend reviewing your projected income to ensure the automated repayment schedule fits comfortably within your operating budget before accepting an offer.

Ready to find the right fit? Review our complete guide to small business loans or check your eligibility today.

Maximum Loan Amount
$5,000 – $500,000

Loan Term
3 to 24 Months

Interest Rates
8% – 35% Simple Interest

Speed
As fast as 24–48 hours

Merchant Cash Advances

Merchant Cash Advances (MCA) for Small Businesses

Access rapid working capital by selling a portion of your future credit card sales or bank deposits—no physical collateral required.

Quick Funding Parameters

  • Advance Amount: $5,000 – $500,000+
  • Repayment Structure: Daily or weekly percentage of credit card sales / ACH revenue withholdings
  • Cost Structure: Factor rates starting at 1.15 to 1.45 (Not an APR)
  • Funding Speed: Same-day to 24 hours

How a Merchant Cash Advance Works

Unlike a traditional short-term business loan with fixed monthly payments, a Merchant Cash Advance (MCA) is a commercial transaction where you sell a set dollar amount of your future receivables at a discount in exchange for immediate lump-sum capital.

Repayments automatically adjust with your business volume: during peak sales periods, you pay off the advance faster; during slower sales cycles, the daily dollar amount remitted drops proportionately.

Key Benefits of an MCA

  • Rapid Access to Capital: Receive funds in as little as 24 hours to cover urgent payroll gaps, bulk inventory buys, or emergency operational needs.
  • Flexible, Sales-Adjusted Repayments: Remittances tie directly to daily credit card processing or daily bank receipts, helping protect cash flow during seasonal dips.
  • No Hard Asset Collateral Required: MCAs rely on historical and projected revenue rather than hard physical assets, unlike traditional equipment financing.
  • Streamlined Qualification: Approval is based primarily on overall bank activity, payment processing volume, and revenue stability—making it accessible even if you are searching for bad-credit or startup loan options.

Understanding Rates, Fees & Total Cost

A Merchant Cash Advance carries a higher overall cost than long-term commercial debt and operates under distinct financial mechanics:

  • Factor Rates vs. APR: MCAs do not use standard interest rates. Instead, a fixed factor rate (e.g., 1.25) is applied to the advance amount. If you accept a $100,000 advance at a 1.25 factor rate, your total repayment obligation is $125,000 ($100,000 x 1.25).
  • Net Proceeds: Upfront origination or underwriting fees may be deducted from your total approval amount, so always verify the actual cash deposited into your bank account.
  • Reconciliation Clause: Confirm whether your agreement includes a reconciliation provision that allows your daily remittance percentage to be adjusted downward if your actual sales volume decreases.
  • Personal Guarantees & Security Interests: Review contract terms carefully to understand any personal liability, confessions of judgment (where applicable), or UCC-1 blanket liens filed against your business assets.

Compare MCA with Other Financing Alternatives

Because the total cost of capital for an MCA is higher than traditional financing, it is always best practice to evaluate other funding products before accepting an offer:

Is an MCA Right for Your Business?

An MCA is best suited for high-volume businesses needing fast, short-term capital to capture immediate revenue opportunities.

Ready to explore your options? Check your eligibility across our small business loans hub or speak with a BitX loan specialist to review transparent, side-by-side financing offers from over 100 lenders in our network. Review our Privacy Policy to see how we protect your financial data.

Maximum Loan Amount
$5,000 – $500,000

Loan Term
3 to 18 Months

Interest Rates
Factor Rates starting at 1.15

Speed
Same-day to 24 hours

Mid-Term Business Loans

Mid-Term Business Loans for Growing Businesses

Secure predictable, medium-term capital to expand your operations, purchase equipment, manage working capital, or consolidate existing high-cost debt into manageable payments.

Quick Funding Parameters

  • Funding Amount: $25,000 – $500,000
  • Repayment Terms: 1 to 5 Years (Monthly or Bi-Weekly ACH)
  • Cost Structure: APRs starting at 6.99% – 18% (Varies by borrower credit and lender)
  • Funding Speed: 3 to 7 Business Days

How Mid-Term Business Loans Work

Mid-term loans bridge the gap between fast, expensive short-term financing and lengthy, traditional bank loans. Spanning 1 to 5 years, these commercial loans offer fixed or predictable monthly payments, making them an ideal choice for businesses that want to fund growth initiatives without draining daily cash flow.

Unlike revenue-based advances that collect daily payments, mid-term loans typically structure payments on a monthly or bi-weekly schedule, providing stability for financial planning and budgeting.

Common Uses for Mid-Term Financing

  • Business Expansion & Upgrades: Open new locations, launch marketing campaigns, or renovate facilities.
  • Capital Equipment: Acquire necessary machinery, vehicles, or technology (See our dedicated equipment financing options for asset-backed deals).
  • Refinancing Debt: Consolidate multiple high-cost short-term business loans or merchant cash advances into a single, lower-rate monthly payment.
  • Working Capital Buffer: Maintain liquidity during expansion phases or inventory buildups.

Understanding Interest Rates, Fees & Total Cost

While mid-term loans offer competitive rates and lower monthly payments than short-term advances, business owners should evaluate the overall cost structure before proceeding:

  • Interest Rates vs. APR: Beyond the base interest rate, evaluate the Annual Percentage Rate (APR), which includes origination fees, processing costs, and broker fees.
  • Impact of Longer Repayment Terms: Spreading repayments over 1 to 5 years lowers your monthly payment burden, but extending the term increases the cumulative interest paid over the life of the loan.
  • Collateral & Guarantees: Depending on the loan size and applicant credit profile, lenders may require personal guarantees, blanket UCC-1 liens, or specific collateral pledges.
  • Prepayment Penalties: Always confirm whether your agreement permits early payoff without incurring prepayment penalty fees.

Compare Mid-Term Loans with Alternative Options

Evaluating your financing options ensures you select the right financial structure for your business lifecycle:

  • Looking for the lowest rates and longest terms? Consider an SBA 7(a) Loan for terms up to 10–25 years.
  • Need rapid funding in 24–48 hours? Explore short-term business loans for urgent capital needs.
  • Need flexible, revolving capital on demand? Learn how a Business Line of Credit allows you to draw and pay interest only on what you use.

Is a Mid-Term Loan Right for Your Business?

Mid-term financing is ideal for established businesses with consistent cash flow looking for a balance between speed, loan size, and manageable monthly payments.

BITX Capital connects you with participating lenders across our marketplace to compare personalized offers side-by-side. Check your eligibility across our small business loans hub or connect with a BitX loan specialist to evaluate rates and repayment terms. View our Privacy Policy to see how we protect your financial information.

Maximum Loan Amount
$25,000 – $500,000

Loan Term
1 - 5 years

Interest Rates
6.99% – 18% APR

Speed
3 to 7 Business Days

SBA 7a Loans

SBA 7(a) Loans for Small Businesses

Access the gold standard of small business financing with government-backed, low-interest funding, extended repayment terms, and manageable monthly payments.

Quick Loan Parameters

  • Funding Amount: $50,000 – $5,000,000
  • Repayment Terms: 10 Years (Working Capital/Equipment) up to 25 Years (Real Estate)
  • Cost Structure: Prime Rate + 2.25% to 4.75% (Variable or Fixed APRs)
  • Funding Speed: 3 to 6 Weeks (Due to government underwriting guidelines)

How SBA 7(a) Loans Work

The SBA 7(a) loan program is the U.S. Small Business Administration’s flagship financing initiative. Rather than lending money directly, the SBA provides a partial government guarantee (typically 75% to 85%) to participating banks and non-bank lenders. This guarantee mitigates lender risk, enabling partner institutions to offer significantly lower interest rates and longer repayment schedules than traditional commercial debt.

Note: The SBA guarantee protects the participating lender against default—it does not relieve the borrower of 100% financial responsibility for full repayment of the loan.

Key Benefits of SBA 7(a) Financing

  • Lowest Commercial Interest Rates: Rates are capped by federal regulation, making SBA loans far more affordable than short-term business loans or a merchant cash advance.
  • Extended Repayment Windows: Reduce monthly cash flow strain with terms up to 10 years for working capital/equipment and up to 25 years for real estate.
  • No Prepayment Penalties on Short Terms: Loans with terms under 15 years carry zero prepayment penalties, giving you the flexibility to pay down principal early without fees.
  • Versatile Capital Deployment: Approved proceeds can support working capital, debt consolidation, equipment, business acquisitions, or qualifying startup business loans.

Approved Business Uses

  • Working Capital & Cash Flow: Fund payroll, seasonal inventory, operational expansion, or marketing campaigns.
  • Refinancing High-Cost Debt: Consolidate high-interest daily or weekly business debt into a single, manageable monthly payment.
  • Equipment & Machinery: Acquire essential business machinery or commercial vehicles (You can also compare this with specialized equipment financing).
  • Business Acquisition or Expansion: Finance the purchase of an existing company, partner buyout, or franchise expansion.

Understanding Costs, Down Payments & Eligibility

Because SBA 7(a) loans offer premium terms, eligibility criteria and underwriting requirements are thorough:

  • Equity Injection / Down Payment: Business acquisitions, commercial real estate, and startup applications typically require a 10% to 20% equity down payment from the borrower.
  • Credit Score Guidelines: Lenders generally seek a minimum personal credit score of 650–680+, though strong business cash flow can help offset lower credit scores.
  • SBA Guarantee Fees: The SBA charges a standard, one-time guaranty fee based on loan size and maturity, which is typically financed directly into the loan balance.
  • Collateral & Personal Guarantees: All owners holding 20% or more equity must provide a personal guarantee. Lenders file a blanket UCC-1 lien on business assets and may request personal real estate collateral for larger borrowing amounts.

Compare SBA 7(a) with Financing Alternatives

If your business needs faster funding or has a shorter operating history, compare SBA loans with other network options:

Is an SBA 7(a) Loan Right for Your Business?

An SBA 7(a) loan is ideal for established business owners looking for maximum capital, low interest rates, and extended payment schedules.

BITX Capital guides you through the SBA application process, matching your business profile with preferred SBA lenders across our network. Use our SBA Loan Calculator to estimate your monthly payments, explore options on our small business loans hub, or connect with a BitX SBA specialist to discuss your options. Review our Privacy Policy to see how we safeguard your personal and business records.

Maximum Loan Amount
$50,000 – $5,000,000

Loan Term
10 to 25 Years

Interest Rates
Prime + 2.25%

Speed
3 to 6 Weeks

Business Line of Credit

Business Lines of Credit for Small Businesses

Access flexible, revolving capital on demand to manage cash flow fluctuations, cover seasonal inventory spikes, and handle unexpected business expenses—paying interest only on the funds you draw.

Quick Credit Line Parameters

  • Credit Limit: $10,000 – $250,000+
  • Repayment Terms: Revolving / 6 to 24 Months per draw
  • Cost Structure: Starting rates from 8% – 25% APR (Varies by credit profile and lender)
  • Funding Speed: 24 to 48 hours

How a Business Line of Credit Works

Unlike a traditional mid-term business loan or SBA 7(a) loan where you receive a lump-sum deposit upfront, a business line of credit functions like an open credit facility.

Once approved for a set limit, you can draw funds whenever your business needs liquidity, repay the drawn balance over time, and continuously reuse your available credit line as principal is paid down. Most importantly, you incur zero interest charges on unused credit reserves.

Key Benefits of a Business Line of Credit

  • On-Demand Liquidity: Keep a safety net active for emergency cash needs, payroll gaps, or fast-moving vendor discounts.
  • Pay Interest Only on What You Use: If you are approved for $100,000 but only draw $20,000, you only pay interest on the $20,000 actively deployed.
  • Revolving Capital Structure: As you make monthly repayments, your available credit automatically replenishes for future draws.
  • Seasonal & Inventory Flexibility: Smooth out revenue drops during off-peak months or purchase bulk stock using an inventory credit line ahead of busy seasons.

Understanding Interest Rates, Fees & Requirements

Line of credit pricing and qualification thresholds depend on your business revenue, time in business, credit profile, and whether the line is secured or unsecured:

  • Interest Rates & Draw Fees: Rates can be fixed or variable. Beyond base APRs, evaluate draw fees (e.g., 1%–2% per withdrawal), origination fees, and annual maintenance or renewal charges.
  • Secured vs. Unsecured Lines: Unsecured credit lines require no physical collateral but demand stronger business revenue and credit scores. Secured credit lines require business assets, receivables, or personal real estate to back the credit facility.
  • Alternative Funding Strategies: For newer businesses or startups seeking initial capital, traditional credit lines may be harder to secure. In these cases, evaluate 0% business credit card stacking to access unsecured promotional financing, or explore targeted startup business loans.

Compare a Line of Credit with Alternative Options

Selecting the right financial structure depends on how you plan to deploy your capital:

Is a Business Line of Credit Right for Your Business?

A revolving business line of credit is an essential financial tool for established and growing businesses seeking continuous access to working capital without accumulating unnecessary debt.

BITX Capital connects you with top lenders across our marketplace to help you compare credit limits, APRs, and draw terms side-by-side. Explore options on our small business loans hub to check your eligibility, or speak with a BitX loan specialist to discuss your options. Review our Privacy Policy to see how we protect your financial data.

Maximum Loan Amount
$10,000 – $250,000

Loan Term
Revolving credit

Interest Rates
8% – 25% APR

Speed
24 to 48 hours

Equipment Financing

Equipment Financing for Small Businesses and Startups

Acquire the essential machinery, commercial vehicles, technology, or specialized tools your company needs while preserving operational cash flow.

Quick Funding Parameters

  • Funding Amount: Up to 100% of Equipment Value ($10,000 – $1,000,000+)
  • Repayment Terms: 2 to 7 Years (Matched to useful asset life)
  • Cost Structure: Starting rates from 6% – 16% APR (Varies by credit profile and equipment type)
  • Funding Speed: 2 to 5 Business Days

How Equipment Financing Works

Equipment financing uses the equipment itself as primary collateral for the loan or lease. Because the underlying physical asset backs the financing, lenders can offer competitive interest rates, lower down payment requirements, and longer repayment terms than unsecured short-term loans.

We help businesses across heavy industries—including construction, manufacturing, transportation, logistics, and healthcare—acquire new or used equipment without paying the full purchase price upfront.

Key Benefits of Equipment Financing

  • Preserve Working Capital: Spread capital expenditures over 2 to 7 years so your liquid cash stays available for payroll, marketing, inventory, and emergency reserves.
  • Predictable Fixed Payments: Structured monthly payments make budgeting straightforward and keep operating expenses manageable.
  • 100% Financing Options: Qualified applicants may cover up to 100% of equipment costs, including soft costs like delivery, setup, and installation.
  • Potential Tax Advantages: Equipment purchases may qualify for accelerated depreciation or tax deductions (such as Section 179). Always consult a qualified tax professional regarding specific deductions.

Tailored Financing Options for Your Business Stage

  • Equipment Financing for Startups: Newer businesses can obtain equipment loans by leveraging owner credit, business plans, and revenue projections. Learn more about navigating initial funding in our guide to startup business loans.
  • Heavy Machinery & Fleet Assets: Transport, construction, and logistics firms requiring specialized rigs or industrial machinery can explore specialized options under our equipment financing program.
  • Down Payments & Upfront Costs: Understand how initial equity contributions impact interest rates and approval terms when structuring equipment debt.

Understanding Loans vs. Leases, Costs, and Terms

Choosing the right structure depends on how long you intend to keep the asset and your business cash flow:

  • Equipment Loans vs. Equipment Leases: Equipment loans grant immediate ownership, while leases offer lower monthly payments with end-of-term buyouts or equipment upgrade flexibility.
  • Asset Depreciation & Useful Life: Financing terms are aligned with the useful operating life of the machinery to prevent carrying debt on obsolete equipment.
  • Down Payment & Guarantees: Down payment requirements depend on applicant credit, equipment age, and lender guidelines. Low- or zero-down options are subject to strict qualification.

Compare Equipment Financing with Other Solutions

If you need capital for non-equipment expenses, compare asset-backed financing against alternative funding products in our network:

Is Equipment Financing Right for Your Business?

Equipment financing is ideal for companies that want to upgrade or expand operational capacity while keeping cash reserves intact.

Estimate your monthly payment schedule, explore options across our small business loans hub, apply online today to compare competing offers from over 100 lenders, or speak with a BitX loan specialist to discuss customized equipment lease or loan terms. Review our Privacy Policy to learn how we protect your personal and business data.

Maximum Loan Amount
Up to 100% of Equipment Value

Loan Term
2 to 7 Years

Interest Rates
6% – 16% APR

Speed
2 to 5 Business Days

Start-Up Business Loans

Startup Business Loans: Explore Funding Options for Your New Business

Launch your new business with purpose-built startup capital designed to fund initial equipment, inventory purchases, digital marketing, and essential operational runway.

Quick Funding Parameters

  • Funding Amount: $5,000 – $250,000+
  • Repayment Terms: 1 to 5 Years (or Revolving)
  • Cost Structure: Starting APRs from 8% – 30%+ (Varies by borrower credit, revenue history, and product structure)
  • Funding Speed: 24 Hours to 2 Weeks

How Startup Business Financing Works

Securing capital for a brand-new company presents unique challenges because startups typically lack years of tax returns or steady business revenue. To bridge this gap, startup lenders evaluate alternative indicators of creditworthiness—such as the owner’s personal credit score, liquid capital reserves, strong business plan, or physical assets being purchased.

Whether you are in the pre-revenue phase or operating under 12 months, several financing vehicles can provide the necessary runway without forcing you to give up equity to outside investors.

Key Benefits of Startup Financing

  • Cover Essential Launch Costs: Fund inventory, leasehold improvements, technology stacks, specialized equipment, and early marketing campaigns.
  • Preserve Cash Flow & Equity: Keep full ownership and control of your company while spreading initial setup expenses over manageable monthly payments.
  • Manage Early Cash Flow: Maintain an operational buffer while developing your customer base and waiting for accounts receivable to materialize.
  • Build Business Credit History: Timely repayments help establish a positive credit profile for your business entity, unlocking larger commercial credit facilities in the future.

Primary Startup Funding Pathways

  • Personal Term Loans for Business: For pre-revenue startups, taking out a dedicated personal loan for commercial use allows you to secure funds based on your personal credit profile and income. Learn more in our detailed guide to personal term loans for business purposes.
  • Asset-Backed Equipment Loans: If your startup needs specialized machinery, tools, or commercial vehicles, the physical asset acts as collateral to secure approval. Explore startup asset options in our guide to equipment financing.
  • Unsecured Business Credit Card Stacking: Early-stage companies can leverage multi-card credit profiles to secure 0% introductory APR lines for 12 to 18 months. Discover how this works in our guide to 0% business credit card stacking.
  • Startup Financing with Limited Capital: Entrepreneurs launching with minimal cash reserves can compare specialized funding programs across our startup business loans hub to evaluate low-down-payment options.

Understanding Qualification, Costs & Personal Guarantees

Because startups carry higher underwriting risk than established businesses, borrowers should review financing obligations carefully:

  • Personal Credit Score Reliance: Pre-revenue financing relies heavily on the owner’s credit profile. Lenders typically look for a personal credit score of 680 or higher.
  • Personal Guarantees & Collateral: Most startup loans require a personal guarantee, meaning you are personally responsible for repayment if the business encounters financial distress.
  • Total Cost of Capital: Always evaluate the Annual Percentage Rate (APR), origination or processing fees, payment frequency, and total repayment obligation before accepting an offer.
  • Realistic Cash Flow Projections: Ensure your projected monthly revenue comfortably covers repayment amounts during slower ramp-up months.

Compare Startup Funding with Established Business Products

As your business grows and establishes consistent monthly revenue, you can refinance or transition into traditional commercial debt:

Is a Startup Business Loan Right for Your New Venture?

Startup financing provides the necessary capital jumpstart to turn your business plan into an operating reality, provided payments align with your financial model.

BITX Capital connects new entrepreneurs with competitive lender networks across the country. Apply online today to compare your startup business loan options, or connect with a BitX startup specialist to discuss your launch plans. Review our Privacy Policy to see how we protect your data throughout the application process.
Maximum Loan Amount
$25K to $500K

Loan Term
5 - 7 years

Interest Rates
7% - 15%

Speed
As fast 7 Days

Personal Term Loans

Personal Term Loans for Business Purposes

Fund your startup or early-stage business by leveraging your personal creditworthiness to secure fast, fixed-rate term capital without needing years of commercial tax returns.

Quick Funding Parameters

  • Funding Amount: $5,000 – $100,000+
  • Repayment Terms: 1 to 7 Years (Fixed monthly installments)
  • Cost Structure: Fixed APRs starting at 6.99% – 24.99% (Varies by personal credit profile and debt-to-income ratio)
  • Funding Speed: 24 to 48 hours

How Personal Term Loans Work for Business

Unlike traditional corporate debt that evaluates business revenue, commercial bank statements, or corporate assets, personal term loans are underwritten based on your individual credit score, personal income, and personal debt-to-income (DTI) ratio.

Upon approval, funds are disbursed in a lump sum into your bank account. You then repay the balance over a fixed timeframe with set monthly payments, making budgeting simple during your company's early launch phase.

Key Benefits of Personal Loans for Commercial Use

  • Ideal for Pre-Revenue Startups: Secure essential capital before your business establishes the revenue history required for traditional small business loans.
  • No Business Asset Collateral Required: Most personal term loans are unsecured, meaning you do not have to pledge commercial real estate, inventory, or machinery to qualify.
  • Fixed, Predictable Payments: Fixed interest rates ensure your monthly repayment amount remains identical throughout the entire loan term.
  • Rapid Capital Access: Streamlined consumer underwriting allows qualified applicants to receive funds in as little as one to two business days.

Understanding Credit Inquiries, Personal Liability & Lender Terms

Because personal financing ties directly to your individual credit profile, evaluate these critical financial considerations before accepting an offer:

  • Soft vs. Hard Credit Inquiries: Checking your initial rate options across our lender network involves a soft credit inquiry, which does not impact your credit score. If you accept an offer and submit a formal application, the lender will perform a hard credit pull, which may temporarily affect your score.
  • 100% Personal Legal Liability: The loan is issued in your name, making you personally responsible for full repayment regardless of your business's success or failure. Delinquencies or missed payments will directly damage your personal credit score.
  • Confirm Permitted Fund Usage: Loan agreements vary by provider. Before deploying funds into your company, confirm that your specific lender explicitly permits personal loan proceeds to be used for commercial entity expenses.
  • Risks of Taking Multiple Loans (Loan Stacking): While some borrowers consider applying for multiple personal loans to aggregate larger capital sums, taking on several debt obligations significantly increases your monthly payment burden and personal financial risk.

Compare Personal Loans with Startup Alternatives

Evaluating alternative funding structures ensures you select the right financial vehicle for your launch strategy:

Is a Personal Loan Right for Your Venture?

A personal term loan is an effective financial bridge for pre-revenue founders with strong personal credit who need fast, fixed-rate capital to start operating.

BITX Capital helps entrepreneurs explore pre-qualified personal financing options from participating lenders across our network. Check your options across our small business loans hub without impacting your credit score, or connect with a BitX loan specialist to discuss your launch plans. Review our Privacy Policy to see how we protect your personal data.

Maximum Loan Amount
$500K

Loan Term
5-7 years

Interest Rates
On Avg 12%

Speed
7 Days

Credit Card Stacking

0% Business Credit Card Stacking for Startups

Leverage multiple business credit cards featuring 0% introductory APR promotions to secure unsecured capital for early-stage expenses—without paying upfront interest or sacrificing equity.

Quick Strategy Parameters

  • Aggregate Funding Limit: $25,000 – $150,000+ (Subject to individual personal credit profile and issuer approvals)
  • 0% Introductory Window: 6 to 18 Months (0% APR on purchases or balance transfers)
  • Post-Promotional Rates: Standard variable APRs ranging from 18% – 29.99%+
  • Funding Speed: 1 to 3 Weeks (Accounts for application sequencing and card issuance)

How 0% Business Credit Card Stacking Works

For pre-revenue startups and early-stage ventures that lack tax returns or revenue history, traditional bank financing can be difficult to secure. Business credit card stacking solves this hurdle by strategically applying for a sequence of business credit cards offering 0% introductory APR promotions.

By aggregating individual credit limits across multiple issuing banks, entrepreneurs can secure $50,000 to $150,000+ in total unsecured credit. As long as minimum monthly payments are made and balances are paid off within the promotional window (typically 6 to 18 months), you gain access to interest-free capital to fund launch expenses.

Key Benefits of Credit Card Stacking

  • 0% Interest Working Capital: Finance marketing campaigns, inventory buys, supplies, or initial payroll without paying interest during the promotional period.
  • No Asset Collateral Required: Business credit cards are unsecured revolving facilities—no real estate, machinery, or business assets are pledged as security.
  • Build Business Credit History: Primary business cards issued under your EIN help establish a commercial credit profile separate from your personal records (issuer reporting rules vary).
  • Preserve Equity & Independence: Maintain 100% ownership of your startup without dilution from angel investors or venture capital firms.

Understanding Credit Inquiries, APR Expirations & Risks

While card stacking offers flexible capital, executing this strategy requires disciplined management to protect your personal and business financial standing:

  • Soft vs. Hard Credit Inquiries: Exploring pre-qualification options begins with soft credit inquiries that do not impact your credit score. However, formal card submissions trigger hard inquiries, and submitting multiple applications within a tight window can temporarily lower your personal credit score.
  • Post-Promotional Interest Rates: Once the 0% introductory APR window expires, any remaining unpaid balance accrues the card's standard variable interest rate. Always have an exit or payoff plan before the promotional period ends.
  • Credit Utilization Management: High balances relative to your total credit limit can elevate your credit utilization ratio, which may temporarily affect your personal credit rating.
  • Strict On-Time Payment Rules: Missing a single payment deadline can trigger penalty APRs and void your 0% promotional rates across affected accounts.

Compare Card Stacking with Alternative Startup Options

Evaluating alternative financing structures ensures you select the right capitalization path for your business model:

Is 0% Credit Card Stacking Right for Your Venture?

Credit card stacking is an ideal solution for founders with strong personal credit (680+ score) who need flexible working capital during the launch phase and have a clear revenue plan to clear balances before promotional rates expire.

BITX Capital helps entrepreneurs evaluate card stacking strategies and sequence applications effectively across our lender network. Explore options on our small business loans hub, apply online today to explore your startup funding options, or speak with a BitX financing specialist to map out your launch plan. Review our Privacy Policy to see how we protect your credit information.

Maximum Loan Amount
$5K -100K

Loan Term
Revolving

Interest Rates
0% Industry Rate

Speed
As fast 15 Days

Inventory Financing

Inventory Financing for Small Businesses and Startups

Unlock liquid capital tied up in inventory, prepare for peak seasonal sales demand, and purchase wholesale stock or raw materials without draining your daily operational reserves.

Quick Funding Parameters

  • Funding Amount: $10,000 – $1,000,000+
  • Repayment Terms: 3 Months to 3 Years (or Revolving Credit Line)
  • Cost Structure: Starting rates from 8% – 24% APR (Varies by inventory valuation, turnover rate, and credit profile)
  • Funding Speed: 2 to 7 Business Days

How Inventory Financing Works

Inventory financing is a specialized form of asset-backed commercial debt or revolving credit where your existing or newly purchased stock serves as collateral for the loan.

Instead of waiting for products to sell to generate cash, inventory financing bridges the working capital gap between purchasing bulk goods from suppliers and collecting final customer revenue. As products are sold, proceeds are used to repay the borrowed balance, replenishing your available capital for future inventory buys.

Key Benefits of Inventory Financing

  • Prepare for Seasonal Demand: Stock up ahead of peak shopping seasons (such as Q4 retail or summer surges) without straining cash flow.
  • Capitalize on Bulk Supplier Discounts: Access larger purchasing tiers to lower your cost of goods sold (COGS) and increase profit margins.
  • Smooth Out Working Capital: Keep liquid capital free for essential overhead, including payroll, facility leases, and digital marketing.
  • Leverage Product Assets: Utilize your tangible inventory value to secure financing, which can lower borrowing thresholds compared to unsecured debt.

Inventory Financing Options Across Business Stages

  • Financing for Established Growing Businesses: Leverage historical sales records and steady product turnover to qualify for asset-backed loans or revolving inventory credit lines.
  • Options for Early-Stage Ventures: New businesses seeking stock capital can evaluate specialized pathways detailed in our guide to startup business loans.
  • Comprehensive Educational Resources: Learn more about structuring inventory loans, valuation methods, and lender criteria across our small business loans hub.

Understanding Inventory Valuation, Collateral & Costs

Because inventory value fluctuates and carries risks of obsolescence or slow sales, lenders evaluate specific risk factors during underwriting:

  • Inventory Valuation Rates: Lenders rarely finance 100% of retail value. Approved funding amounts typically range from 50% to 80% of the wholesale or liquidation value of the eligible stock.
  • Product Eligibility & Turnover: Fast-moving consumer goods, durable retail products, and raw materials carry higher loan-to-value (LTV) ratios than perishable, custom, or highly specialized items.
  • Total Cost of Capital & Audit Fees: In addition to interest rates or factor rates, review origination fees, inventory appraisal costs, or periodic field audit fees charged by the lender.
  • Collateral & Security Interests: Lenders place a UCC-1 lien on the financed inventory and may require a personal guarantee or secondary blanket lien on general business assets.

Compare Inventory Financing with Alternative Funding Solutions

Selecting the right financial facility depends on your supply chain structure and operating timeline:

  • Need ongoing, multi-purpose working capital? Consider a revolving business line of credit for flexible cash access.
  • Need fast cash to cover immediate, non-inventory expenses? Explore short-term business loans with rapid approval times.
  • B2B company waiting on unpaid customer invoices? Unlock cash tied up in outstanding receivables using factoring receivables.
  • Purchasing heavy machinery or warehouse tools to handle stock? Use dedicated equipment financing to back long-term asset purchases.

Is Inventory Financing Right for Your Business?

Inventory financing is ideal for product-based businesses, wholesalers, e-commerce retailers, and distributors with strong sales channels looking to turn inventory into immediate growth capital.

BITX Capital matches your company with specialized inventory lenders across our nationwide network. Explore options on our small business loans hub, apply online today to explore your eligibility, or speak with a BitX loan specialist to review side-by-side financing terms. View our Privacy Policy to see how we protect your financial data.

Maximum Loan Amount
$500K - $20M

Loan Term
Revolving

Interest Rates
8% - 15%

Speed
As fast 15 Days

Factoring Receivables

Invoice Factoring for Small Businesses

Turn unpaid net-30, net-60, or net-90 B2B customer invoices into immediate working capital without taking on traditional loan debt or waiting months to get paid.

Quick Funding Parameters

  • Funding Amount: $10,000 – $5,000,000+
  • Advance Rate: 80% to 95% of total invoice face value
  • Cost Structure: Factoring fees starting at 1% – 5% per 30 days
  • Funding Speed: 24 to 48 hours

How Invoice Factoring Works

Invoice factoring (also known as accounts receivable factoring) is an asset-backed commercial transaction, not a traditional loan. Instead of incurring debt, you sell eligible outstanding B2B or government invoices to a factoring provider at a slight discount in exchange for immediate cash.

  1. Submit Invoices: You deliver goods or complete services for your business clients and issue an invoice with payment terms (e.g., net-30 or net-60).
  2. Receive Upfront Advance: The factoring company advances 80% to 95% of the invoice value directly into your bank account within 24 to 48 hours.
  3. Customer Settlement: Your customer pays the factoring provider according to the standard invoice due date.
  4. Final Reserve Rebate: Once paid, the factor remits the remaining 5% to 20% balance back to you, minus a small factoring fee.

Key Benefits of Invoice Factoring

  • Eliminate Cash Flow Bottlenecks: Meet weekly payroll, purchase raw materials, and cover overhead expenses without waiting 30 to 90 days for client payments.
  • Debt-Free Working Capital: Because you are selling an asset (receivables) rather than borrowing money, factoring does not create a monthly debt liability on your balance sheet.
  • Underwritten on Customer Credit: Qualification depends primarily on the creditworthiness of your B2B customers, making factoring accessible even if your business is young or has past credit challenges.
  • Scales Automatically with Revenue: As your sales volume grows and you issue larger invoices, your available funding pool increases proportionately.

Specialized Industry Solutions

  • Transportation & Freight: Freight carriers and owner-operators can accelerate fuel and maintenance cash flow using dedicated trucking invoice factoring.
  • Manufacturing & Distribution: Finance raw material procurement and production runs while waiting for wholesale distributors to settle terms.
  • Staffing & Professional Services: Cover weekly payroll commitments while corporate clients process invoices on extended billing cycles.

Understanding Recourse vs. Non-Recourse, Fees & Contract Terms

Factoring agreements carry specific contractual structures that every business owner should evaluate:

  • Factoring Rates vs. APR: Factoring fees are calculated as a percentage of the total invoice value (e.g., 1.5% per 30 days outstanding). The longer your customer takes to pay, the higher the total cumulative fee.
  • Recourse Factoring: Under a recourse agreement, your business retains ultimate financial responsibility. If your customer fails to pay the invoice due to insolvency or default, you must buy back the invoice or replace it with a valid alternative.
  • Non-Recourse Factoring: The factoring company absorbs the credit risk if your customer defaults due to credit insolvency. However, non-recourse protection usually carries higher fees and excludes customer payment disputes over work quality.
  • Customer Notification & Verification: Factoring providers verify invoice validity with your client and direct payment to a designated lockbox, so clear customer communication is essential.
  • Minimum Volume Requirements: Review contracts carefully to confirm whether the provider requires you to factor all invoices or allows selective ("spot") factoring.

Compare Invoice Factoring with Alternative Financing Options

Selecting the ideal financial instrument depends on your business model and capital requirements:

Is Invoice Factoring Right for Your Business?

Invoice factoring is an ideal capital solution for B2B companies, distributors, freight carriers, and service providers whose cash flow is locked up in unpaid customer accounts receivable.

BITX Capital connects you with top-tier factoring partners across our nationwide lender network. Explore options on our small business loans hub, apply online today to unlock your unpaid receivables, or speak with a BitX cash flow specialist to compare factor rates and advance percentages. Review our Privacy Policy to learn how we protect your commercial data.

Maximum Loan Amount
Up to 100% on Invoice Value

Loan Term
30/60/90 days

Interest Rates
1.15% - 4.5%

Speed
As fast 5 Days

Businesses That Are Ready to Achieve Their Goals

At BitX Capital, we believe in the power of ambition. Our platform is designed to help ambitious individuals and businesses turn their ideas into reality. We believe that with the right resources and support, anyone can achieve their goals and make a positive impact in the world. By providing access to funding and expert guidance, we empower our customers to pursue their dreams and make their ambitions a reality. Join us and let your ambition drive you to success.

Minimum Requirements for Small Business Loans

Find the Right Business Financing for Your Goals

Every business has different financing needs. Whether you’re launching a startup, purchasing equipment, managing cash flow, or expanding an established company, comparing your funding options can help you make a more informed decision.

BITX Capital helps small business owners explore potential financing solutions through its lender network. We can help you evaluate available options and understand important differences in eligibility requirements, interest rates, fees, repayment terms, and total borrowing costs.

Take the next step toward financing your business. Explore your options, prepare your financial information, and consider which funding solution best fits your business plan and projected cash flow.

Start exploring business financing with BITX Capital today. Approval, available funding, and financing terms depend on the lender and your qualifications.

Disclaimer: These requirements represent minimum network qualifications. Specific eligibility thresholds, interest rates, and loan terms vary depending on the funding product and lender selected.

Credit Score

0 +

With BITX Capital, credit score requirements vary by financing type and lender. Some options may be available for scores in the 500s, while a score of 600 or higher may improve your eligibility.

Time in Business

Startups

For BITX Capital, lender requirements for time in business vary from 0 months to 1–2 years. However, having at least six months in business may improve your chances of securing funding.

Monthly revenue

$ 0 K+

For BITX Capital, pre-revenue businesses may qualify, while established businesses may need at least $8,000 in monthly revenue. Requirements vary by lender and loan type.

BitX is bonded and insured

Your financial data is protected by bank-level 256-bit SSL encryption and hosted on Salesforce’s secure enterprise cloud infrastructure, ensuring your application remains private and fully protected.

BitX comes from experience

Backed by 10+ Years of Financial Expertise

Founded in 2014 by President Todd Rowe, BitX Capital brings over a decade of small business lending experience and an A+ rating from the Better Business Bureau (BBB). Our team of dedicated loan specialists provides personalized guidance through every step of the funding process.

BitX is trusted, safe, and secure

Licensed Broker & Bank-Grade Security

BitX Funding LLC is a licensed commercial finance broker (CT NMLS ID: 2324279 | CA Financing Law License No. 60DBO-142631). Your financial data is protected by multi-factor authentication, 256-bit bank-grade encryption, and cloud-based enterprise infrastructure.© 2026 BitX Funding LLC. BitX is a service mark of BitX Funding LLC.

BitX is ever-evolving

Industry Accredited & Community Connected

We maintain active partnerships across a network of over 100 premier lending institutions and are proud members of the Fairfield Chamber of Commerce and local business development networks, keeping us at the forefront of small business financing trends.

Small business loan specialists are available 6 days a week

BITX Capital helps small businesses explore financing options to achieve their goals. Our loan specialists can guide you through the process and help you find potential funding solutions. Don’t let limited capital hold you back—contact us today to explore your options and take the next step toward growing your business.

Small Business Loan FAQs

To get a small business loan fast, start by assessing your financial needs and preparing a detailed business plan. Research different lenders and their requirements, then gather all necessary documentation, such as financial statements and credit reports. Finally, submit your application and be prepared to discuss your business plan with potential lenders.
The best small business loans provide funds to cover various business needs. The process involves applying to a lender, specifying the loan purpose, and providing necessary documentation. Lenders assess your creditworthiness, revenue, and business history to determine eligibility and loan terms. Once approved, you receive a lump sum or line of credit to use for your business. You’ll repay the loan with interest over a set period, following a schedule agreed upon with the lender. The loan terms, interest rates, and repayment schedules vary depending on the lender and loan type, so it’s essential to understand these terms before borrowing.
To qualify for quick business loans, you typically need to have a solid business plan, a good credit score, and sufficient business revenue. Lenders will also look at your business history, so having at least six months of operations can be beneficial. Additionally, gathering necessary documentation such as financial statements, tax returns, and business licenses will strengthen your application.
Small business loans can be either secured or unsecured, depending on the lender and type of loan. Secured loans require collateral, such as property or equipment, which the lender can claim if you default on the loan. Unsecured loans, on the other hand, do not require collateral but may come with higher interest rates and stricter eligibility criteria due to the increased risk for the lender.
Yes, small business loans are available for startups, though they can be more challenging to obtain than loans for established businesses. Startups often need to provide a strong business plan, demonstrate potential for growth, and may need to offer personal guarantees or collateral. Some lenders also offer specialized loan programs designed specifically for new businesses.
The minimum credit score for a business loan typically varies by lender, but most traditional lenders require a score of at least 600 to 650. Some alternative lenders may accept lower scores, but this often comes with higher interest rates and less favorable terms. It’s vital to check with individual lenders to understand their specific credit score requirements.
Obtaining a fast small business loan can be challenging, but it is certainly possible. The difficulty largely depends on factors such as your credit score, the financial health of your business, and the lender’s criteria. Some online lenders and financial technology companies specialize in quick approvals and funding, sometimes within 24 to 48 hours, albeit often at higher interest rates.
Yes, you can get a business loan online. Many online lenders and small business loan startup companies offer streamlined application processes, quick approvals, and fast funding. These online options can be particularly beneficial for businesses that need access to capital quickly.

BITX Capital is a financial technology platform and loan broker, not a direct lender. We work with a network of participating lenders to provide business financing options across various financial products, including SBA loans, lines of credit, and short-term working capital.

Because terms vary by lender, loan type, credit profile, and time in business, Annual Percentage Rates (APRs), factor rates, repayment frequencies, and origination fees differ across offers. APRs range from approximately 6% for traditional SBA loans up to higher factor rates for short-term revenue-based advances, with repayment terms spanning between 3 months and 25 years. All loan offers, rates, and terms are provided directly by participating lenders upon review of your complete financial application, and BITX Capital does not guarantee loan approval or specific funding timeframes.